What is a Governmental Component Unit?
Jan 9, 2021
A governmental component unit is a legally separate organization for which the elected officials of the primary government are financially accountable. It can also be another organization for which the nature and significance of their relationship with a primary government are such that exclusion would cause the reporting entity’s financial statements to be misleading due to close relations and financial integration with the primary government.
When Does a Government Have Financial Accountability for an Organization?
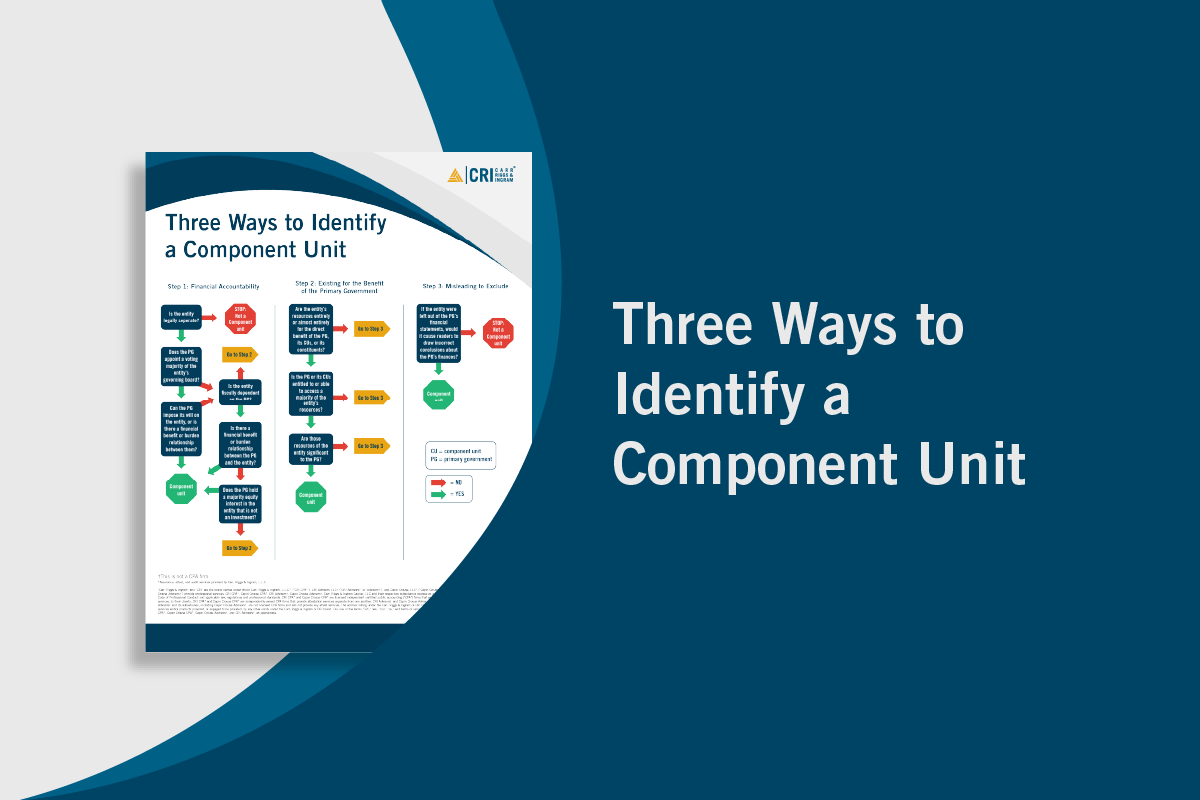
Typically, a government has financial accountability for an organization when the answer to the three questions below is “yes”:
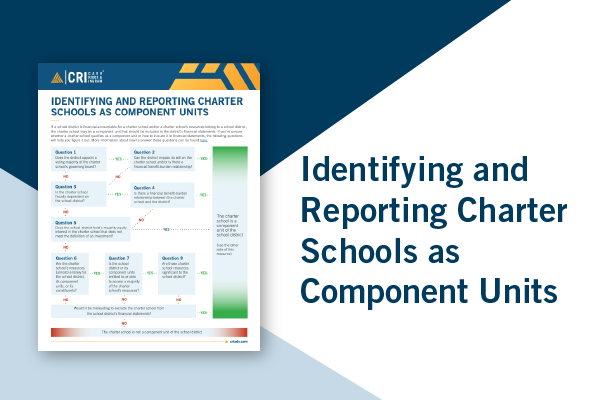
- Are the economic resources received or held by the separate organization entirely or almost entirely for the direct benefit of the primary government, its component units, or its constituents?
- Is the primary government or its component units entitled to, or have the ability to otherwise access, a majority of the economic resources received or held by the separate organization?
- Are the economic resources received or held by an individual organization that the specific primary government is entitled to, or has the ability to otherwise access, significant to that primary government?
Ultimately, the primary government’s management must exercise professional judgment to determine which entities should be included as component units. Most often, governmental component units are typically entities or nonprofits whose purpose is to benefit a government by soliciting contributions and managing those funds.
What Are Examples of Governmental Component Units?
Examples of governmental component units include:
- Utility companies (water, electricity, wastewater, etc.)
- Foundations
- Charter schools
- Alumni associations
- Housing authorities
- Not-for-profit corporations
How Are Component Units Presented in Government Financial Statements?
Depending on the relationship to the government, a government’s component units are presented in one of two ways: blended or discretely presented.
A blended component unit’s financial information is reported within the government’s financial statements (as if it were part of the government), and a discretely presented component unit’s financial information is reported in a separate column in the government’s government-wide financial statements.
Get Assistance Evaluating Component Unit Accountability
Contact your CRI advisor for help determining what, if any, governmental component units may be your entity’s financial responsibility.